At these reference rates, an unchanged dollar payment requires fewer euros. Your actual settlement cost also depends on the bank quote, fees and hedges.
Published 2026-10-31 · Observation period 2026-10-30
Evidence behind the decision
ECB · Currency exposure
Open the source desk for the available observations and their status.
The question: when does a change in stocks become meaningful for a feedstock purchasing decision?
Worked example · 20 October 2026Numerical basis: observations for 2 and 9 OctoberHistorical assessment
One signal, three questions
For a buyer, the final question is not how much stocks changed. It is whether that change improves or weakens a specific supply option.
01
Change
Stocks excluding the SPR fell from 424.134 to 415.577 million barrels: a decline of 8.557 million barrels between 2 and 9 October.
02
Consequence
A stock draw may reduce the availability buffer, but its cause is unclear without examining production, imports, exports and consumption.
03
Path
A purchasing decision requires an assessment of grade, origin, destination, delivery timing and actual availability.
A practical implicationDo not substitute an aggregate figure for cargo evidence. First identify which part of your requirement depends on this market.
Evidence of the change
Source: EIA, Table 4 · All figures in million barrels
Stocks
2 October
9 October
Weekly change
US commercial, excluding SPR
424.134
415.577
−8.557
Cushing
24.745
26.607
+1.862
Important counter-evidence: Cushing stocks rose while total stocks fell. A national decline cannot therefore be treated as evidence of the same shortage at every delivery hub.
What do we know, and what remains unknown?
The EIA reference measures US commercial crude oil stocks, excluding the SPR, at the end of the week.
Observation period: 2–9 October 2026.
This reference does not confirm a grade, a cargo for sale, an offer price or delivery availability to your destination.
Briefing reference
US commercial crude oil stocks EIA · Table 4 Observation: 9 October 2026
Compare the aggregate signal with the grade, delivery hub and commercial terms relevant to your requirement.
From signal to decision
Read the observation, compare counter-evidence, then identify the cargo, contract or settlement evidence needed for your decision.
What evidence comes next?
Moving from market interpretation to a supply assessment requires a clear specification, quantity and delivery window. Supply evidence and route constraints can then be assessed within that scope.
CurrencyNot applicable; this is an inventory quantity
Exact publication timeNot recorded in the available record
Definition: US commercial crude oil stocks, excluding the Strategic Petroleum Reserve, at the end of the week. This is not a price, an inventory of a particular grade or an offer of supply.
ECB · Observation: 19 October 2026 Source reviewed: 20 October 2026
US dollars per euro: a daily reference rate, not an executable rate. Timing differences, conversion costs and the bank or counterparty's dealing rate require separate assessment.
Geopolitics & trade / Research note 02 · v2.2
Hormuz: the price of keeping oil moving
Export recovery can coexist with expensive, fragile delivery. The decision is which risks a cargo margin can absorb.
Independent research note · Not live pricing
Evidence and decision review: 29 October 2026 · Review due: 30 October 2026
The judgement
For an Asian refinery or physical trader selecting crude for the next 7–30 days, a higher regional export volume is not sufficient evidence to make a firm delivered commitment. The commercially scarce asset may be a suitable vessel, valid cover, a workable discharge window or cash to finance delay—not the barrel at origin. This is our inference from the evidence below, not a cargo-specific finding.
Preferred course: maintain a Gulf option and a genuinely executable alternative, compare their grade-adjusted delivered contribution on the same arrival window, and commit only after the downside fits both margin and liquidity. Do not pay a reliability premium merely for a different country name; verify that the alternative removes the binding dependency.
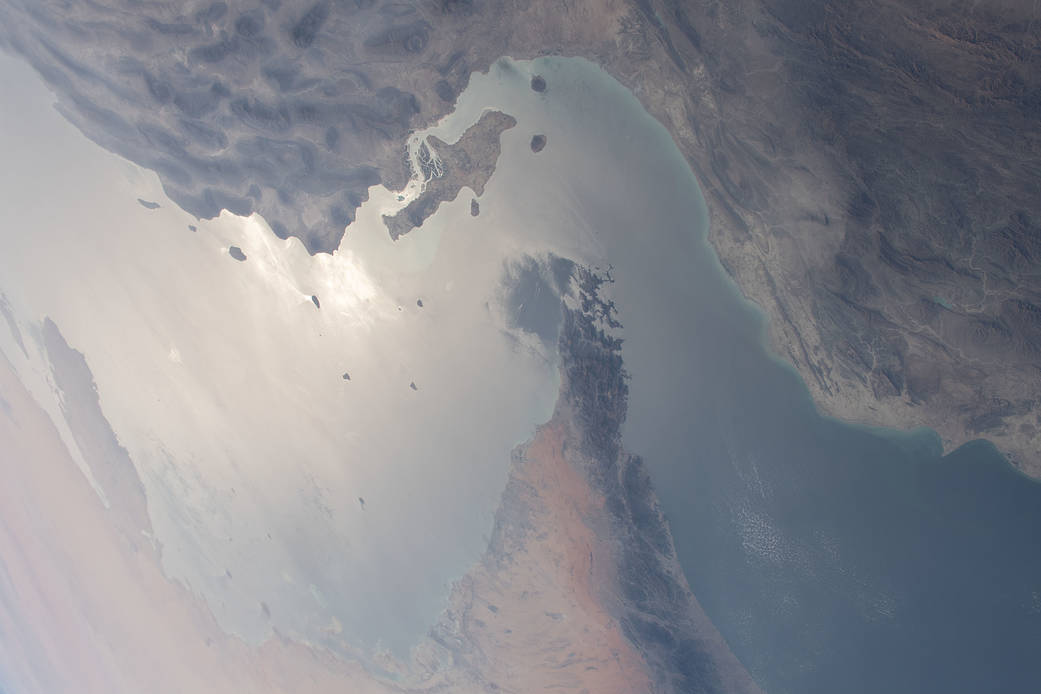
Strait of Hormuz · Archive photograph, 24 Mar 2021. NASA / ISS · Source · Use conditions
29 October review: verify the delivery chain
The EIA outlook remains dated 6 October, with inputs closed on 1 October; the IEA freight commentary is dated 21 October. MARAD still lists Advisory 2026-011 as active. The review retains the conditional judgement and adds a practical check on the evidence behind a delivery claim. It verifies no new transit total, cargo quotation or arrival. [1, 2, 4]
For the buyer, the next step is to trace the cargo from loading through any transfer to final discharge, then compare a firm delivered offer with a usable fallback. Align product, geography and event date before comparing flow totals; count each cargo once. Test whether more crossings reflect new loadings or an old queue clearing. Until the chain and arrival window are confirmed, keep the margin and cash conditions in place. This is our decision checklist, not a new measurement of flows.
Three checks before relying on a flow signal
Cargo identity: match loading records, vessel identity, transfers and discharge evidence. Resolve missing links before treating movements as delivery.
Comparable evidence: align product, boundary, period, event, unit and revision status. A new retrieval date does not make the observation newer.
Decision threshold: obtain a valid offer, carrier acceptance, applicable cover and a workable arrival window; test stressed contribution and peak cash needs.
1. What changed: recovery without normalisation
EIA’s 6 October outlook estimates that Middle Eastern production shut-ins fell from 10.9 million barrels/day in May to 5.8 in August and 4.8 in September. September’s improvement is real within that estimate series, but 4.8 million barrels/day still represents production unavailable. These are estimates, not a measurement of October cargo availability. [1]
The later IEA commentary, published 21 October, reports elevated freight costs for mid-October. Its narrative observations below concern different routes and are not interchangeable offers. They show why changing origin does not automatically escape a stressed tanker market. [2]
The positive signal and the adverse signal are not contradictory: more oil can reach the market while using more vessel time and more expensive logistics. EIA’s own outlook assumes gradual restoration, yet warns that volatility can exceed what its central forecast depicts. Its inputs closed on 1 October; it cannot settle conditions on 27 October. [1]
EIA estimated shut-in production · million barrels/day · 2026 [1]
Period
Estimate
May 2026
10.9
August 2026
5.8
September 2026
4.8
Calculated from the rounded published estimates: September is 1.0 million barrels/day below August (about 17%) and 6.1 below May (about 56%). A reduction in shut-ins is not the same quantity as an increase in delivered cargoes.
Selected freight observations in IEA’s 21 October commentary · mid-October 2026 · USD/barrel [2]
Route
Reported cost
Middle East Gulf → Asia · large crude tanker
More than USD 37/barrel
US Gulf Coast → Singapore · crude transport
Around USD 33/barrel
Different route definitions and potentially different voyage assumptions: do not subtract these figures to rank offers. They are dated narrative observations, not executable quotes or a new price feed.
2. Geostrategy: access is not the same as independence
A binary “open or closed” view misses how coercive leverage can operate through uncertainty, delay and cost even while trade continues. This is a strategic mechanism, not a claim about any government’s hidden intent. Protective arrangements, bypass infrastructure and transfers can sustain flows without creating an equally usable route for every flag, operator, cargo and destination.
EIA documents the September disruption and partial restoration of Saudi Arabia’s East-West pipeline, a route intended to bypass Hormuz. Our inference: redundancy should be tested by common points of failure—terminal, pipeline, passage, carrier, cover and finance—not by counting route names. A bypass can remove one chokepoint while leaving another dependency decisive. [1]
The bargaining consequence is uneven. A producer may recover export volume while conceding value to secure transport; a buyer may obtain a cargo discount while paying more to receive it. Control over reliable capacity and timing can command a premium. This does not imply that every shipowner gains: insurance, operating exposure and contractual liabilities can absorb that premium.
The strategic trade-off differs by actor. In our assessment, exporters have reason to preserve monetisable access; importing governments have reason to diversify supply while limiting delivered inflation; an actor capable of disrupting passage can impose costs without stopping every shipment. None of this proves a government’s intent. It explains why diplomatic restraint, physical recovery and commercial normalisation can proceed at different speeds—and why a desk should not turn a political headline straight into a larger position.
3. Geoeconomics: compare the margin you can realise
For a refiner, origin price is an incomplete ranking rule. Compare expected product realisation per barrel of feedstock after grade/yield adjustment, less acquisition, logistics, insurance, financing and the costs retained under the actual contract. For a trader, use the contracted sale netback instead of refinery product realisation. Keep all alternatives in one currency, unit and arrival window.
Define headroom as contribution after known costs minus the firm’s required contribution. Test whether the additional uninsured or unrecoverable cost of an adverse delivery case consumes that headroom. If it does, the discount has not bought enough protection. This is a decision identity; no cargo economics or incident probability is estimated here.
Avoid double counting: do not add freight or insurance already included in a delivered quotation. Use only costs and liabilities borne by the evaluated party. Also test cash, not just profit: delay may extend working-capital use or require cash before any recovery from insurance or a counterparty. A profitable estimate can still exceed available liquidity.
Run freight and delay as separate stress axes using a valid alternative freight offer and the next feasible delivery slot, rather than invented attack odds. For each case, show contribution and peak cash draw. The commercial breakpoint is the first case that falls below required contribution or exceeds the liquidity limit. Compare the cost of reserving a fallback with the loss it can actually avoid; an unavailable or too-late alternative has no usable option value.
4. The contract can move the risk back to the buyer
BIMCO’s VOYWAR 2025 model addresses war-risk-related cancellation, routing, freight adjustment and insurance-cost allocation. These provisions matter only if incorporated and as modified in the signed documents; they are not universal rules for this trade. [3]
The commercial test is whether the sale promise, carriage rights, insurance and payment documents remain aligned after disruption. A carrier may retain a right that the seller has not mirrored in its delivery commitment. Likewise, shifting transport responsibility does not automatically transfer title, every loss or bank acceptance. Review the actual contractual chain with the relevant advisers; a country or an Incoterm label alone is not a sufficient answer.
5. Three paths, with observable decision triggers
These are conditional planning cases for the next 7–30 days, not probability forecasts. For 30–90 days, prioritise substitution readiness and independent delivery capacity rather than extrapolating today’s quoted spread.
Planning path
Evidence to watch
Decision implication
Adaptation under strain
Flows recover but firm freight, cover or arrival windows remain restrictive.
Keep a second executable supply path; limit commitment to the stressed margin and cash capacity.
Operational easing
Successive valid offers show lower total delivered cost and firmer performance, not just a diplomatic headline.
Reduce contingency spend only after the physical and contractual improvement is confirmed.
Renewed interruption
Carrier acceptance, cover or a required terminal window is withdrawn or materially changed.
Recalculate exposure and invoke the contracted fallback; do not defend the old trade on sunk effort.
6. Turn the thesis into a bounded commitment
Procurement should request a Gulf case and an alternative for the same specification and arrival window. The operator should confirm carrier, loading and discharge feasibility and fallback rights. Treasury should test the peak cash draw during delay; the commercial lead should set a maximum adverse cost and the last date on which substitution remains useful. Keep quote validity and decision expiry explicit.
Conditional Go requires executable counterparties and voyage, confirmed applicable cover and documents, positive stressed contribution, sufficient cash and a fallback that can still be used. If a required condition is unresolved, Hold the firm commitment while preserving the option. If a condition fails and cannot be repaired before the decision expires, decline or reprice that transaction. Safety and legal eligibility are prerequisites, not losses that a higher margin can simply compensate.
Still needed: A binding freight/insurance offer, confirmed voyage and the buyer’s margin and cash limits.
7. What would weaken or overturn this judgement?
The strongest contrary case is sustained operational normalisation: executable freight and cover improve across successive fixing windows, delivery times shorten, and grade-adjusted Gulf offers retain an advantage after all costs. Then paying a large premium for alternatives can destroy value. EIA’s recovery assumptions are a reason to watch for that outcome, not to assume it has already arrived.
Our thesis has greater confidence as a structural decision rule than as a forecast of the next cargo. No current carrier acceptance, binding freight, insurance offer, refinery yield slate, bank decision or buyer cash position was supplied. Without these inputs, we cannot choose a winning cargo or quantify its risk-adjusted return.
Evidence, method and limits
Scope: crude procurement for an Asian refinery or physical trader; 7–30-day commitment and 30–90-day preparedness. This synthesis separates source estimates, source commentary and our conditional analysis. Source windows differ; none is a live quote for 27 October. No attack probability is calculated: incident counts without a comparable exposure denominator cannot support one. The analysis does not establish a vessel’s clearance, legal eligibility or insurance acceptance.
MARAD’s active advisory provides an operational-risk backdrop; it does not resolve the economic choice between two cargoes. Its U.S.-flag scope should not be generalised to every vessel. [4]
Analysis and translations: CURRENT & PASSAGE. This note replaces the introductory briefing; previous versions remain in publication history. No cargo-specific conclusion is made.
This is a work derived by CURRENT & PASSAGE from IEA material and CURRENT & PASSAGE is solely liable and responsible for this derived work. The derived work is not endorsed by the IEA or its Member countries in any manner.
The dossier stays open while material commercial consequences remain. Review dates govern the freshness of each analysis; they do not remove the topic.
Select a decision context. Each path leads to material currently available.
About & approach
CURRENT & PASSAGE connects market evidence with the assessment of energy, industrial supply and commercial requirements. Start with the decision, test the evidence and define the missing conditions.
Three questions before considering options
01
What needs to be resolved?
A shortfall in quantity, a specification mismatch or unreliable delivery? Each calls for a different line of enquiry.
02
Which constraint governs the decision?
Usable grade, arrival date, destination or transaction terms? An option only makes sense in relation to these constraints.
03
What evidence is still missing?
Market stocks are not the same as access to a cargo. Which specification, document or delivery condition remains unverified?
The approach and source directory explain how evidence is used; the local brief helps you define your own constraints.
Selected questions
Does the stock figure determine my purchase price?
No. It measures aggregate stocks at the end of the week. Your purchase price depends on specification, location, timing, quantity and transaction terms. Reference definition
When does this become relevant to my commercial requirement?
When the feedstock, quantity, destination and delivery window are specified. That enables an assessment of the route; it does not confirm supply.
Where should I start?
Start with the dated briefs and their sources. Each identifies the commercial question, relevant evidence and next step.
Does your feedstock budget reflect the rise in LNG costs?
NBS · China · 2026-10-11 / 2026-10-20
Analysis reviewed
For: LNG procurement
What changed: NBS reports LNG at CNY 6,749.4 per tonne for 11–20 October, up 9.1% against the preceding period in its table.
Decision: For a gas buyer, a fixed budget may no longer match the newly reported benchmark.
Still needed: A valid supplier offer for the required specification, volume and delivery point.
Next step: Recheck a valid offer against grade, quantity and delivery.
Sources & scope
Limits An aggregate benchmark, not an offer, an import price or today’s price.
What changed: The ECB reference moved from USD 1.1193 per EUR on 23 October to 1.1188 on 26 October; this was the latest observation visible at the 27 October review.
Decision: If payment is in dollars and the budget in euros, the same dollar amount requires more euros.
Still needed: Payment amount and date, hedge coverage, fees and an executable bank rate.
Next step: Reprice settlement using the bank’s valid quote and fees.
Sources & scope
Limits A reference rate, not an executable rate; relevant to EUR/USD exposure.
National stocks fell. Is your delivery hub short as well?
EIA · US stocks · 2026-10-09 / 2026-10-16
Analysis reviewed
For: Crude buyers · Refinery planners
What changed: US commercial crude stocks were 412.517 million barrels on 16 October; Cushing stocks rose by 0.987 million barrels from the previous week.
Decision: A national draw does not establish the same position at every hub or for every grade.
Still needed: Grade-specific inventory, a deliverable cargo, loading slot and arrival window.
Next step: Request evidence for the actual grade and delivery hub.
Sources & scope
Limits US stocks do not establish cargo availability in Canada, Mexico or a particular port.
New retail data. The right basis for your fuel contract?
ANP · Brazil · 2026-10-18 / 2026-10-24
Analysis reviewed
For: Brazilian fuel buyers · Pricing teams
What changed: ANP now lists its survey for 18–24 October, with station-level data marked updated on 26 October. This confirms availability, not a new price or price change.
Decision: The earlier publication delay is no longer the decision issue; the relevant fuel, location and contract basis still need to match.
Still needed: The selected survey row, fuel specification, locality, tax basis and a comparable valid offer.
Next step: Match fuel, location and tax basis before using the reference.
Sources & scope
Limits Retail survey availability is not a wholesale or import quotation. No survey price has been extracted or presented here.
September purchasing prices rose 6.9% from a year earlier; factory-gate prices rose 5.0%. For overseas industrial buyers, the question is which costs reach a supplier's offer. Different index baskets prevent a company-margin conclusion. Check the input, reset formula and validity period behind any surcharge; company cost and order evidence remain missing.
For: Manufactured-goods importers and industrial suppliers
China's cost signal: what reaches an export quote?
Use the national signal to test a supplier's cost explanation.
For: Manufactured-goods importers and industrial suppliers
Observed: 2026-09 · Analysis reviewed: 2026-10-31
China's national purchasing and factory-gate selling-price indices describe different baskets; an exporter's offer reflects its own inputs and contract.
In September, purchasing prices rose 6.9% from a year earlier and factory-gate prices 5.0%; both rose 1.2% month on month. Their annual gap cannot measure company margins or establish a new monthly squeeze.
For a contract-linked cost adjustment, the route runs through the supplier's actual input mix and agreed reset terms. Inventory and hedges may delay transmission; the national indices do not verify it.
Changed selling terms offer a competing explanation. Company costs and orders remain unverified. A documented input reset matched to a revised offer would support cost transmission; unchanged selling terms would weaken the procurement concern.
What would change this view?
Watch comparable indices and documented supplier revisions; test whether the cost actually reaches the offer.
Sources, dates & scope
A documented input-to-quote linkage for the specific supplier and contract.
Commercial crude stocks excluding the strategic reserve fell by 1.892 million barrels in the week ending 23 October. For crude buyers, the issue is whether the required hub and grade are also tighter. National stocks alone cannot answer it. Check regional flows and confirmed delivery terms before treating the draw as a reason to pay more.
National crude stocks describe a buffer. Usable supply is a particular grade at a particular hub and arrival date; that distinction governs comparisons with overseas alternatives.
EIA's accepted observations show commercial crude, excluding the strategic reserve, falling from 412.517 million barrels on 16 October to 410.625 million on 23 October—a calculated draw of 1.892 million barrels.
The draw becomes a delivery concern only if the required hub and grade are also tighter. Current regional availability is the missing bridge. Production, imports, exports and refinery use have not been isolated as causes.
Confirmed alternative supply or an unchanged local balance could preserve workable options. Regional stocks, flows and firm cargo terms could change the assessment; these national observations establish neither a local shortage nor a price or freight move.
What would change this view?
Watch regional stocks, flow components, firm cargo terms and the next accepted EIA observation.
Sources, dates & scope
Current hub-and-grade availability and a firm delivery option for the required arrival window.
Preliminary third-quarter growth slowed but stayed positive: 0.5% in the EU and 0.4% in the euro area, quarter on quarter. Exporters need to know whether their own customer sectors changed. Aggregate GDP does not establish weaker imports. Check orders and inventories before changing shipment commitments; sector detail and revisions remain material gaps.
For: Exporters and industrial suppliers serving European buyers
Observed: 2026-Q3 compared with 2026-Q2 · Analysis reviewed: 2026-10-31
EU growth: follow the customer orders behind the headline
Test customer demand before translating slower growth into shipment commitments.
For: Exporters and industrial suppliers serving European buyers
Observed: 2026-Q3 compared with 2026-Q2 · Analysis reviewed: 2026-10-31
A supplier serving Europe faces customer orders, rather than one regional growth rate. EU and euro-area figures also cover different economies.
Eurostat's preliminary third-quarter growth estimate was 0.5% quarter on quarter in the EU, after 0.7%, and 0.4% in the euro area, after 0.6%. Growth slowed but stayed positive; the incomplete estimates are revisable.
A commercial effect would run through an exposed sector, customer orders and inventories, then import requirements. Aggregate GDP cannot verify those links or separate demand, inventory and net-export contributions.
Firm orders could contradict the broad signal. Country and sector detail may change the reading; no recession, import or market-price forecast follows from this release.
What would change this view?
Verify the revision notice; the retained header and body disagree on its next date.
Sources, dates & scope
The exposed customer's orders and inventory needs, plus relevant country/sector detail.